Equipment financing lets a business buy or lease machinery, vehicles and systems, with the equipment usually securing the funding. Wrenpeak Lending Group, a small-business funding broker in Lake Charles, Louisiana, explains loans, leases and equipment finance agreements for Calcasieu Parish contractors, restaurants and practices and sends requests to lending partners, which decide and set every rate and term.
| Built for | Machines, vehicles, kitchen lines, clinical systems |
|---|---|
| Structures | Loans, leases, equipment finance agreements |
| Secured by | The equipment itself |
| Local context | 419 construction and 337 restaurant employers in Calcasieu Parish (CBP 2023) |
| Who decides | The lending partner |
How does equipment financing work?
A partner pays the seller, and you repay over a term roughly matched to how long the equipment will be useful. The equipment secures the arrangement, so many partners ask for less from the rest of the business than they would for an unsecured loan. Quotes, invoices or bills of sale are central to the file: the partner needs to know exactly what it is financing and what it is worth.
Loan, lease or EFA: deciding who owns the machine
| Structure | Who owns it | At the end | Fits when |
|---|---|---|---|
| Equipment loan | The business, immediately, subject to the lender's lien | Lender's lien is released once the last payment clears | You plan to keep the asset for most of its life |
| Equipment finance agreement (EFA) | You, with the funder secured by the asset | You own it outright after the final payment | You want to own it under a short, plain contract |
| Lease | The lessor during the term | Hand it back, extend, or buy at the contract price | The asset dates quickly or you want to upgrade |
Lease terms vary widely. A fair-market-value lease lets you buy at the end for whatever the asset is worth then; a nominal-buyout lease ends with a token purchase price and behaves much like a loan. Ask which you are being offered and what the total of all payments plus the buyout comes to.
How to finance construction equipment
Excavators, skid steers, compact track loaders, trailers and work trucks are among the most common requests from contractors. Calcasieu Parish had 419 construction employer establishments in 2023, 266 of them specialty trade contractors, and 205 of the 419 had fewer than five employees (U.S. Census Bureau, County Business Patterns 2023). For a small crew, buying a machine outright can drain the cash needed for payroll on the next job.
Partners look at the age, hours and resale value of the machine, the contractor's history and the work in hand. Contractor pickups and service vans can be financed as equipment; we do not take requests from trucking or freight-hauling businesses. Contractor and construction financing has more on how partners view the trades.
Used equipment
Used machines are financed every day, but expect closer scrutiny. Partners may ask for an inspection, photographs, hour-meter readings or an appraisal, and may set a shorter term because the asset has less life left. Private-party sales need clean title and a lien search on the seller, so the equipment is not already pledged to someone else.
Kitchens, clinics and storefronts
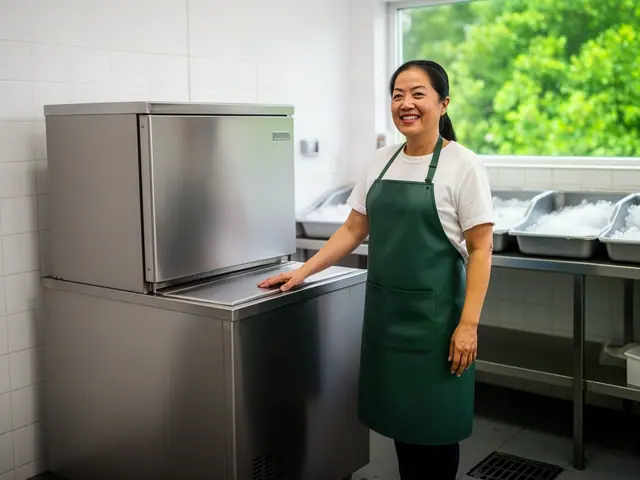
The same structures apply outside construction. Calcasieu Parish had 337 restaurants and other eating places, 137 offices of physicians and 68 offices of dentists in 2023 (U.S. Census Bureau, County Business Patterns 2023). Walk-in coolers, hood systems, combi ovens, dental chairs, imaging units and point-of-sale systems all qualify as equipment. If you are opening a new place, funding a new restaurant in Lake Charles, LA separates kitchen equipment from build-out and opening cash.
One machine or many small buys?
An equipment loan or EFA ties the funding to one asset and one schedule, which usually suits a significant purchase. A line of credit is better for small, frequent buys, such as tools, parts and repairs, that do not justify their own contract. A large purchase with a long working life can also fit a business term loan, especially when several items are bought together with installation and build-out costs.
Before you sign
- Get the total of all payments, plus any buyout or balloon, in dollars.
- Confirm who owns the equipment during the term and at the end.
- Ask whether insurance on the equipment is required and who must be named on it.
- Check for early payoff terms and charges.
- Read what happens if the equipment is lost, stolen or damaged.
The four steps explain our role, and local data and contacts cover the parish.
By Wrenpeak Lending Group · Updated